Company liquidation in Turkey is the only way a joint stock or limited company ceases to exist: a company that stops trading, closes its bank account and dismisses its staff remains on the trade registry with every tax, social security and filing obligation intact until it is dissolved, liquidated and deleted under the Turkish Commercial Code (Türk Ticaret Kanunu). This article explains how the shareholders dissolve the company and with what majority, who the liquidator is and what the law requires of them, how creditors are called through the Trade Registry Gazette and why nothing can be distributed for three months after the third call, how the liquidation is taxed and when the final returns are due, how employees are terminated and paid, how the surplus reaches a foreign shareholder, how the company is deleted and what survives the deletion, how branches and liaison offices of foreign companies are closed, and what it takes to repair a company that was abandoned instead of liquidated.
- Dissolution needs seventy-five percent of the share capital in a joint stock company and two thirds of the votes represented plus a majority of the capital in a limited company.
- At least one liquidator must be a Turkish citizen resident in Turkey; the company trades as "in liquidation" and only through the liquidator.
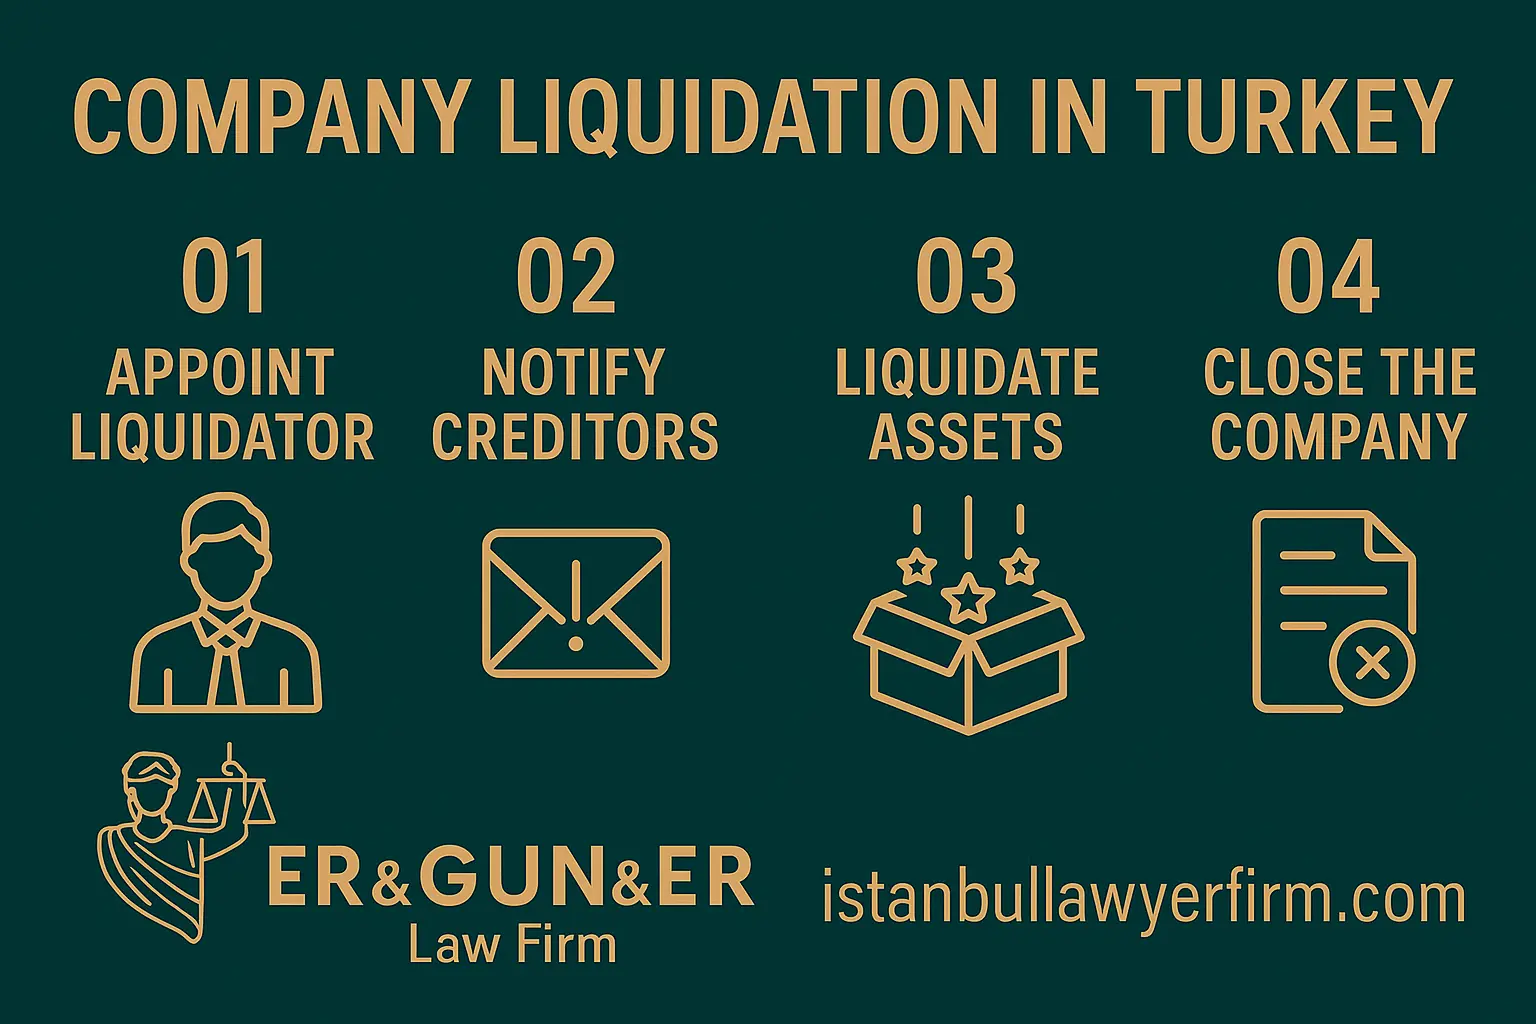
- Creditors are called three times, a week apart, in the Trade Registry Gazette; the remaining assets are distributed three months after the third call at the earliest.
- The liquidation period is taxed as a whole; the liquidator is personally liable for tax left unpaid when assets are distributed.
- A company that cannot pay its debts in liquidation goes to the bankruptcy court; a company abandoned without liquidation keeps generating liabilities for its registered managers.
Dissolution: the resolution, the majority and the entry into liquidation
A company is dissolved by a resolution of its general assembly, by the expiry of a term in its articles, by bankruptcy, by a court judgment on a shareholder's application for just cause, or by operation of law, and the voluntary route is the resolution. In a joint stock company (anonim şirket) the dissolution resolution requires the affirmative vote of shareholders holding at least seventy-five percent of the share capital, in a limited company (limited şirket) two thirds of the votes represented at the meeting and the absolute majority of the whole capital with voting rights; the articles may raise either threshold but not lower it. The resolution is taken at a meeting held under the ordinary rules, with the ministry representative where the law requires one, is notarised and registered with the trade registry (Ticaret Sicili Müdürlüğü) within the registration period, and is announced in the Trade Registry Gazette (Türkiye Ticaret Sicili Gazetesi); from the registration the company's name carries the words "tasfiye halinde", in liquidation, on every document.
Foreign shareholders vote through a representative holding a notarised and apostilled power of attorney, translated and notarised in Turkey, or through the parent company's own resolution where the shareholder is a company, in which case the parent's resolution and the authority of its signatories are proved with apostilled registry extracts; in our practice the resolution of the Turkish company and the parent's resolution are drafted together, because the trade registry examines the chain of authority before it registers the dissolution. A single-shareholder company, which is common among foreign-owned subsidiaries, dissolves by the written decision of its sole shareholder in the same form.
Two further routes lead to liquidation without a resolution and matter in 2026. A company whose capital is below the statutory minimum, two hundred and fifty thousand lira for a joint stock company and fifty thousand for a limited company, and which has not increased it by the end of 2026 is deemed dissolved under the 2024 amendment and enters liquidation by operation of law; and a company struck off the registry ex officio without liquidation, which happened to many dormant companies under the transitional provisions, can be restored by the commercial court for liquidation on the application of a creditor or a shareholder. Our practice page on establishing a company in Turkey covers the formation side; this article covers the exit. Practice may vary by authority and year.
The liquidator: appointment, nationality, powers and liability
Liquidation is conducted by one or more liquidators (tasfiye memuru) appointed by the articles or by the general assembly; where neither appoints, the board members of a joint stock company or the managers of a limited company are the liquidators by law. At least one liquidator must be a Turkish citizen with their place of residence in Turkey, a requirement that catches foreign-owned companies whose only director sits abroad, and that in our practice is met by appointing a Turkish lawyer or accountant as co-liquidator rather than by moving a foreign director's residence. The liquidators are registered and announced, and from the registration they alone represent the company; the board's and the general assembly's powers are confined to what liquidation requires, and the general assembly keeps the approval of the accounts, the appointment and removal of liquidators and the final decisions.
The liquidators draw up an opening inventory and balance sheet, call the creditors, collect the receivables, sell the assets, pay the debts, terminate the contracts and the employees, keep the books and file the returns, and prepare the final balance sheet; they sell assets by private sale unless the general assembly decides on an auction, and they may continue the business only as far as its orderly winding up requires. A liquidator who finds that the company's debts exceed its assets must notify the commercial court at once, and the court ordinarily declares the company bankrupt; voluntary liquidation is therefore a procedure for solvent companies, and a creditor is paid in full or the file becomes a bankruptcy.
Liquidators are liable to the company, the shareholders and the creditors for loss caused by a breach of their duties, under the same provisions as directors, and the tax law adds a stricter rule: a liquidator who distributes assets before the company's taxes are paid is personally liable for the unpaid tax. The remedy of the shareholders against a liquidator is removal by the general assembly or by the court for just cause, and the remedy of a creditor is the liability action within the limitation period; in our experience the exposure is managed by paying every public debt before any shareholder receives a lira and by documenting each sale at a value a later auditor can defend. Our practice page on the Turkish business and commercial lawyer covers the corporate side.
Creditors: the three calls, the deposits and the three-month wait
The liquidators call the creditors to declare their claims by three announcements in the Trade Registry Gazette, each a week after the last, and on the company's website if it has one, and they notify the creditors known from the company's books by registered letter; the calls are the device that protects the liquidators and the shareholders, because a creditor who was called and did not come forward cannot later complain that they were overlooked. Claims that are known from the books but not declared, claims not yet due and claims in dispute are not ignored: the amount of a known undeclared claim is deposited with a bank designated by the Ministry, and the amount of a disputed or not-yet-due claim is deposited with a notary, unless the creditor is secured or the shareholders' distribution is made conditional on its payment.
The remaining assets may not be distributed to the shareholders until three months have passed from the third call. The period was one year under the original Code, six months from 2016 and three months since the amendment of November 2021, and the court may permit an earlier distribution where the circumstances show no risk to creditors; the three months are the floor of every liquidation timetable, and with the registration of the dissolution, the three weekly calls and the final registration added, a solvent company with no disputes is deleted ordinarily within six to nine months of the resolution. Practice may vary by authority and year.
A creditor who comes forward is paid from the liquidation assets, in full and in the order the liquidators choose, since the ranking rules of the Enforcement and Bankruptcy Law apply only in bankruptcy; a secured creditor is paid from the security, and a creditor whose claim the liquidators reject sues the company in liquidation in the ordinary way, with the liquidation continuing around the dispute and the deposited amount waiting for the judgment. Public creditors are a special case in practice rather than in law: the tax office and the Social Security Institution are notified of the liquidation, and the trade registry does not complete the deletion while their debts are open. Our practice page on enforcement and bankruptcy law in Turkey covers what happens when the company cannot pay.
Taxation of the liquidation and the final returns
The Corporate Tax Law treats liquidation as a tax period of its own. The period from the start of the financial year to the registration of the dissolution is a short accounting period with its own corporate tax return; the liquidation period begins on the registration date and ends on the registration of the liquidation's completion, with each calendar year inside it a separate liquidation period with its own return, and the whole liquidation finally assessed as one. The liquidation profit is the difference between the net assets at the end of the liquidation and at its start, with distributions to shareholders during the liquidation added back and capital contributions deducted, so that the tax falls on the gain realised by selling assets above book value; where the final assessment shows that too much was paid in an interim period, the excess is refunded. The final liquidation return is filed within thirty days of the registration of the completion, and the taxes of the earlier periods are corrected in it.
Value added tax is charged on the sale of the company's assets during liquidation, including the sale of real estate and vehicles to shareholders, and the company's VAT registration stays open until the last return; the tax office is notified of the dissolution and of the completion within the periods the Tax Procedure Law sets for changes of status, the electronic invoice and ledger accounts are closed with the final declarations, and the stamp tax on the resolutions and the sale agreements is paid as they are made. Benefits taken under an investment incentive certificate whose conditions are not met before the company ceases are recovered with interest, and the incentive file is closed with the Ministry before the deletion.
The surplus distributed to shareholders above the paid-in capital is a dividend, and dividend withholding is applied by the company at the rate in force, ten percent since the end of 2021, reduced for a foreign shareholder to the rate of the double taxation treaty on proof of residence; the net amount is transferred abroad through the bank with the liquidation documents, and the withholding is reported in the company's last withholding return. The tax office may audit the company for the limitation period, five years from the start of the year following the tax year, after the deletion, and the former liquidators answer the audit, so the books and records are kept for ten years under the Commercial Code and at least five under the tax law. Our practice page on the tax lawyer in Turkey covers the liquidation returns and the audits.
Employees, contracts and the assets
The closure of the business is a valid reason for terminating employment under the Labour Law, but it does not change what the employee is owed. Each employee receives notice according to length of service, two weeks under six months, four weeks under eighteen months, six weeks under three years and eight weeks beyond, or pay in lieu; severance pay (kıdem tazminatı) after one year of service, thirty days' gross wage for each year up to the annual ceiling; the pay for unused annual leave; and the wages and overtime earned to the last day, with the social security exit notification filed within the period the Institution sets and the final premiums paid. In our practice the terminations are documented in a mutual termination agreement (ikale) with a release where the employee agrees, because a claim brought after the company is deleted is brought against the liquidators and the shareholders who received the surplus, not against a company that no longer exists.
Contracts are terminated or assigned: the lease by notice under its terms or by agreement with the landlord, supply and service contracts by their termination clauses, and licences and distribution agreements by the mechanisms they contain, with the counterparties' claims for early termination settled or deposited as creditor claims. Permits and registrations are cancelled, from the municipal business licence to sector licences, trademark registrations are assigned to the parent or allowed to lapse, and domain names and software licences are transferred before the accounts that pay for them are closed. The bank account is the last thing closed, after the final tax and the distribution.
Assets are sold at market value, with a valuation report for real estate and for sales to shareholders or affiliates, because a sale below value is a disguised distribution that the tax office taxes and a creditor can attack; real estate passes through the land registry with the liquidator's registered signature, vehicles through the notary, and shares in other companies through their own registries. Our note on social security rights in Turkey covers the employees' entitlements, and our practice page on the Turkish labour and employment lawyer the termination process.
Completion: the final balance sheet, the distribution and the deletion
When the debts are paid or deposited and the three months have passed, the liquidators prepare the final balance sheet and the distribution plan, the general assembly approves them and discharges the liquidators, and the surplus is distributed to the shareholders in proportion to their paid-in capital unless the articles provide otherwise, in cash unless the shareholders agree to take assets. The liquidators then apply to the trade registry for the deletion of the company, declaring that the liquidation is complete and that the books have been deposited for safekeeping; the registry deletes the company and announces the deletion, and the company's legal personality ends with the deletion, not with the dissolution.
Three things survive the deletion. If an asset or a liability turns up afterwards, a shareholder, a creditor or a former liquidator may ask the commercial court to re-register the company for an additional liquidation (ek tasfiye) limited to the steps the court orders, and the company reappears on the registry for that purpose only. The liquidators' and directors' liability survives for the limitation period, and so does the tax office's audit power. And a creditor whose claim was overlooked applies for the additional liquidation to reach what was distributed, which is why the deposits for known and disputed claims are made before the distribution rather than after.
A liquidation can also be stopped: so long as no distribution has begun, the general assembly may resolve to revoke the dissolution and continue the company, with sixty percent of the capital in a joint stock company, and the liquidators register the revocation; a company dissolved by the expiry of its term or by bankruptcy can revoke only in the cases the Code allows. In our practice the revocation is used where a buyer appears for the business during the liquidation, which is sold as a going concern rather than piecemeal. Our practice page on the commercial contract lawyer in Turkey covers the share and business sales that replace a liquidation.
Branches, liaison offices and companies that were never liquidated
A branch of a foreign company is not a Turkish company and is not liquidated; it is closed by a resolution of the foreign company's competent body, apostilled and translated, registered with the trade registry where the branch is registered, after the branch's tax returns are filed, its employees terminated, its social security registration closed and its tax office notified, and the deletion is announced; the foreign company remains liable for the branch's debts, because the branch never had a separate personality. A liaison office (irtibat bürosu), which operates under a permit from the Ministry of Industry and Technology's foreign investment directorate and may not trade, is closed by notifying that directorate with the closure documents and the final activity report, closing the office's tax file, which exists only for withholding on salaries, and terminating the staff; the Ministry's file is the record that the office never earned income, and a closure notice that reads otherwise invites an assessment on the foreign parent.
Many foreign investors learn years later that the Turkish company they thought was closed still exists. The company has filed no returns, so the tax office has assessed it on estimates with penalties and interest; the Social Security Institution has assessed premiums on the last registered employees; the trade registry has sent warnings to the last registered address; and the managers registered at the time, often former employees who left years ago, carry personal liability for the public debts under the rules that make company representatives liable for taxes and premiums the company cannot pay. In filings we handle the repair starts with a search of the trade registry, the tax office, the Institution and the enforcement offices, continues with the late returns, the penalty reductions available for voluntary disclosure and the instalment plans, and ends with the ordinary liquidation described above, because there is no shortcut from an abandoned company to a deleted one.
A foreign shareholder's exit by sale rather than liquidation avoids all of this and is usually cheaper: the shares are sold to a buyer who takes the company with its history, the seller's liability is limited to the warranties in the share purchase agreement, and the company is never dissolved. Where no buyer exists and the company is clean, the liquidation is the exit; where the company is not clean, the liquidation is still the exit, after the repair. Our note on starting a company and the residence permit in Turkey covers the entry that this article closes.
Frequently asked questions
- What majority is needed to dissolve a Turkish company? Seventy-five percent of the share capital in a joint stock company; two thirds of the votes represented at the meeting and the absolute majority of the capital with voting rights in a limited company. The articles may set a higher threshold.
- Can a foreign director be the liquidator? Yes, but at least one liquidator must be a Turkish citizen resident in Turkey, so a foreign-owned company appoints a Turkish co-liquidator, usually its lawyer or accountant.
- How long does a liquidation take? At least three months from the third creditor call in the Trade Registry Gazette before anything can be distributed; with the registrations and the tax clearance, ordinarily six to nine months from the dissolution resolution for a solvent company without disputes.
- What if the company cannot pay all its debts? The liquidator must notify the commercial court, which ordinarily declares the company bankrupt. Voluntary liquidation pays every creditor in full; it is not a procedure for insolvent companies.
- How is the liquidation taxed? As one liquidation period, with a return for each calendar year inside it and a final return within thirty days of the completion's registration; the gain on assets sold above book value is corporate tax, the sales bear VAT, and the surplus above paid-in capital is distributed with dividend withholding at the current rate, reduced by treaty.
- Can the company be brought back after deletion? Only by a court order for an additional liquidation where an asset or a liability is discovered afterwards, and only for that purpose. Before any distribution has begun the shareholders can revoke the dissolution and continue the company.
- What happens if the company is simply abandoned? It remains registered, is assessed for taxes and premiums on estimates with penalties, and its registered managers become personally liable for the public debts; the repair is the late filings, the penalty reductions and then an ordinary liquidation.
Author: Av. Mirkan Günay Topcu, Managing Partner, ER&GUN&ER Law Firm, Istanbul Bar No. 67874. He advises foreign shareholders and parent companies on the dissolution and liquidation of Turkish companies, branch and liaison office closures, liquidator appointments, creditor and tax procedures, employee terminations and the repair of abandoned companies. Education: Istanbul University Faculty of Law (2018); Galatasaray University, LL.M. (2022).
Profile: Av. Mirkan Günay Topcu. LinkedIn: Profile. Istanbul Bar Association: Official website. Related practice page: enforcement and bankruptcy lawyer in Turkey.